Rated 4.8/5 by 10,000+ users

Rated 4.8/5 by 10,000+ users

MSME 45-Day Payment Calculator

Find the due date for a micro or small supplier’s bill, whether the expense will be disallowed, and the interest owed under the MSMED Act.

Check a Supplier Bill

Supplier type (as per Udyam registration)
Written credit agreement with the supplier?
Already disallowed in FY 2025-26
It was unpaid past the due date when FY 2025-26 closed, so Section 43B(h) of the Income-tax Act, 1961 adds it back to that year’s income. You can claim it in the year you pay. Interest keeps running until you do.
Payment due by
27 Mar 2026
Days late
231
Interest at 17.25% p.a.
₹57,243
Amount disallowed
₹5,00,000
Extra tax for that year
₹1,30,000
Interest is compounded monthly at three times the RBI Bank Rate (Section 16, MSMED Act) and is indicative. Use the Bank Rate in force for your period. The rule applies to FY 2025-26 under Section 43B(h) and from FY 2026-27 under Section 37(2)(g) of the Income-tax Act, 2025. Disputed or rejected supplies follow different timelines, so confirm edge cases with your CA.
hisabkitab’s supplier ageing report shows every unpaid bill by age, so MSME dues don’t slip past the limit.Start free

3 Simple Steps

How It Works

1. Enter the bill

1. Enter the bill

1. Enter the bill

Amount, acceptance date, payment date and whether you have a written credit agreement.

Amount, acceptance date, payment date and whether you have a written credit agreement.

Amount, acceptance date, payment date and whether you have a written credit agreement.

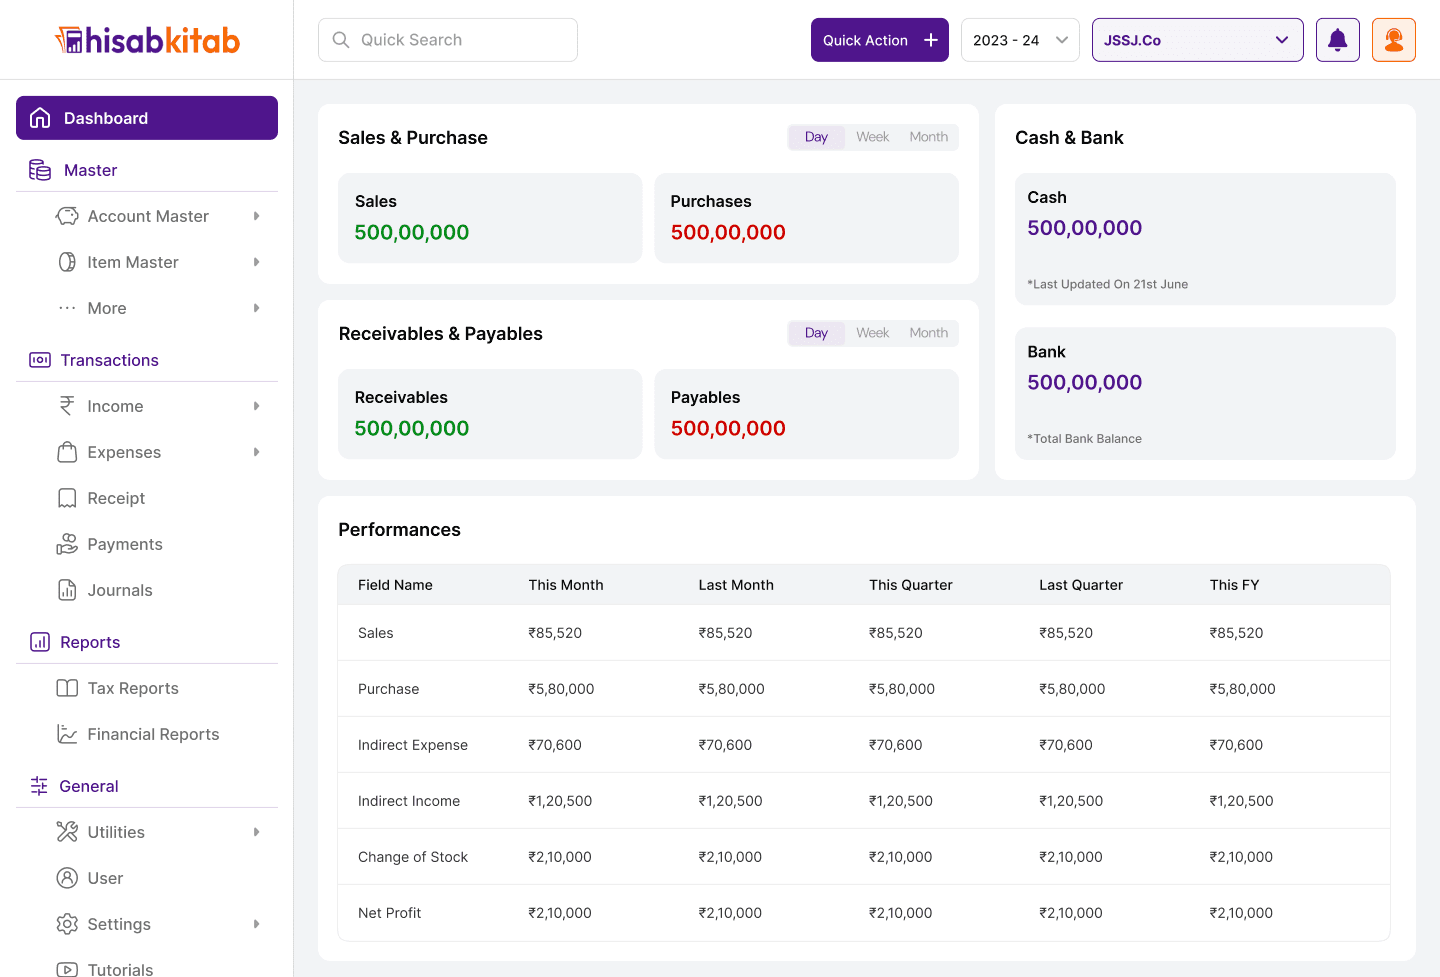
hisabkitab accounting dashboard showing sales, purchases, receivables and performance

2. See the deadline and risk

2. See the deadline and risk

2. See the deadline and risk

Get the due date, days late, interest and the amount that could be disallowed.

Get the due date, days late, interest and the amount that could be disallowed.

Get the due date, days late, interest and the amount that could be disallowed.

3. Pay before 31 March

3. Pay before 31 March

3. Pay before 31 March

Clear overdue MSME dues before year-end to keep the deduction in the same year.

Clear overdue MSME dues before year-end to keep the deduction in the same year.

Clear overdue MSME dues before year-end to keep the deduction in the same year.

hisabkitab accounting dashboard showing sales, purchases, receivables and performance

Track every supplier bill by age in hisabkitab

Track every supplier bill by age in hisabkitab

Industries That Use Our Features

Industries That Use Our Features

Versatile Accounting and Billing Software for Every Sector

  • Retail Businesses

  • Traders

  • IT Firms

  • Wholesale Businesses

  • Retail Businesses

  • Traders

  • IT Firms

  • Wholesale Businesses

  • Retail Businesses

  • Traders

  • IT Firms

  • Wholesale Businesses

  • Retail Businesses

  • Traders

  • IT Firms

  • Wholesale Businesses

  • Retail Businesses

  • Traders

  • IT Firms

  • Wholesale Businesses

  • Retail Businesses

  • Traders

  • IT Firms

  • Wholesale Businesses

  • Startups

  • Pharma & Healthcare

  • Freelancers

  • MSMEs

  • Startups

  • Pharma & Healthcare

  • Freelancers

  • MSMEs

  • Startups

  • Pharma & Healthcare

  • Freelancers

  • MSMEs

  • Startups

  • Pharma & Healthcare

  • Freelancers

  • MSMEs

  • Startups

  • Pharma & Healthcare

  • Freelancers

  • MSMEs

  • Startups

  • Pharma & Healthcare

  • Freelancers

  • MSMEs

What is the MSME 45-day payment rule?

The rule comes from Section 15 of the MSMED Act, 2006. A buyer must pay a micro or small enterprise within the period agreed in writing, and that period cannot be more than 45 days from acceptance of the goods or services. With no written agreement, the limit is 15 days. Since FY 2024-25, Section 43B(h) of the Income-tax Act ties your tax deduction to this deadline, so a late payment can push the expense into a later year.

Who does the rule apply to?

The rule depends on the supplier, not the buyer:

  • It applies when the supplier is a micro or small enterprise registered on Udyam as a manufacturer or service provider.

  • It does not apply to payments to medium enterprises.

  • Traders registered on Udyam, wholesale or retail, are outside the MSMED Act payment rules, so the disallowance does not apply to them.

  • The buyer can be any business that claims the purchase as an expense.

How is the disallowance worked out?

If an amount owed to a micro or small supplier is still unpaid on 31 March and its 15 or 45-day deadline has already passed, it is added back to that year’s taxable income. You get the deduction in the year you actually pay. If you pay late but within the same financial year, the deduction stays in that year, though interest is still payable.

Example: goods worth ₹12,00,000 accepted on 5 February 2026 under a 45-day agreement are due by 22 March 2026. If they are paid on 24 May 2026, ₹12,00,000 is disallowed in FY 2025-26 and allowed in FY 2026-27.

Interest on late payment to MSMEs

Section 16 of the MSMED Act makes the buyer pay compound interest, with monthly rests, at three times the Bank Rate notified by the RBI, from the day after the due date. Following the RBI’s 7 October 2026 policy the Bank Rate is 5.75%, which puts the interest at 17.25% a year. Check the current rate before you rely on a figure. Under Section 23 of the MSMED Act, this interest is never allowed as a tax deduction.

Section 43B(h) or Section 37(2)(g)?

The Income-tax Act, 2025 came into force on 1 April 2026. For FY 2025-26 and earlier years the rule is Section 43B(h) of the 1961 Act. From FY 2026-27 the same rule sits in Section 37(2)(g) of the new Act. The calculator labels each result with the section that applies to the year of purchase.

How to stay compliant

A few habits keep MSME dues out of trouble:

  • Record each supplier’s Udyam category in your vendor master.

  • Note the date goods or services were accepted, not just the invoice date.

  • Put credit terms of up to 45 days in writing.

  • Review the supplier ageing report every week and again before 31 March.

More free tools from hisabkitab: GST Invoice Generator, GSTIN Validator, E-Way Bill Validity Calculator, Amount in Words, HSN & SAC Code Finder, Accounting Software Finder.

FAQs

Do the 45 days run from the invoice date?

What if there is no written agreement with the supplier?

Does Section 43B(h) apply to payments to traders?

Does it apply to medium enterprises?

What interest rate applies on late payment?

Is the interest paid to an MSME tax-deductible?

Is the calculator’s result final?
Experience the convenience of the
Complete Mobile Accounting Solution

Experience the convenience of the
Complete Mobile Accounting Solution

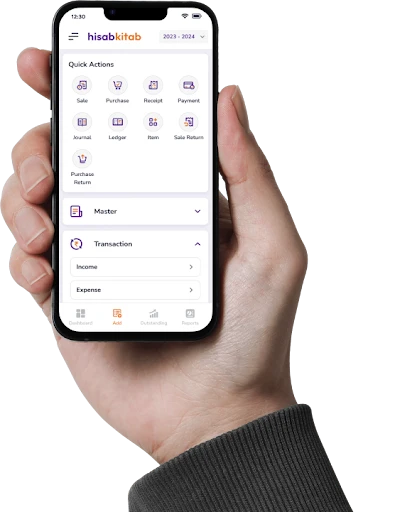
hisabkitab mobile accounting app on a phone
QR code to download the hisabkitab mobile app

Available On

Experience the convenience of the
Complete Mobile Accounting Solution

hisabkitab mobile accounting app with quick actions for sales, purchases and receipts
hisabkitab mobile accounting app on a phone
QR code to download the hisabkitab app
QR code to download the hisabkitab mobile app

Available On